Business term loan
Borrow a set amount and repay under an agreed schedule.
Keep in mind: Match the repayment schedule to realistic business cash flow.
Explore this option →Get clear on funding the equipment your business needs, from the asset quote to the final repayment.
Explore the information first. Our team can help you understand the next step.
The initial review does not involve a hard credit enquiry. If you choose to proceed, a formal credit application may involve a hard enquiry, which can affect your credit score.
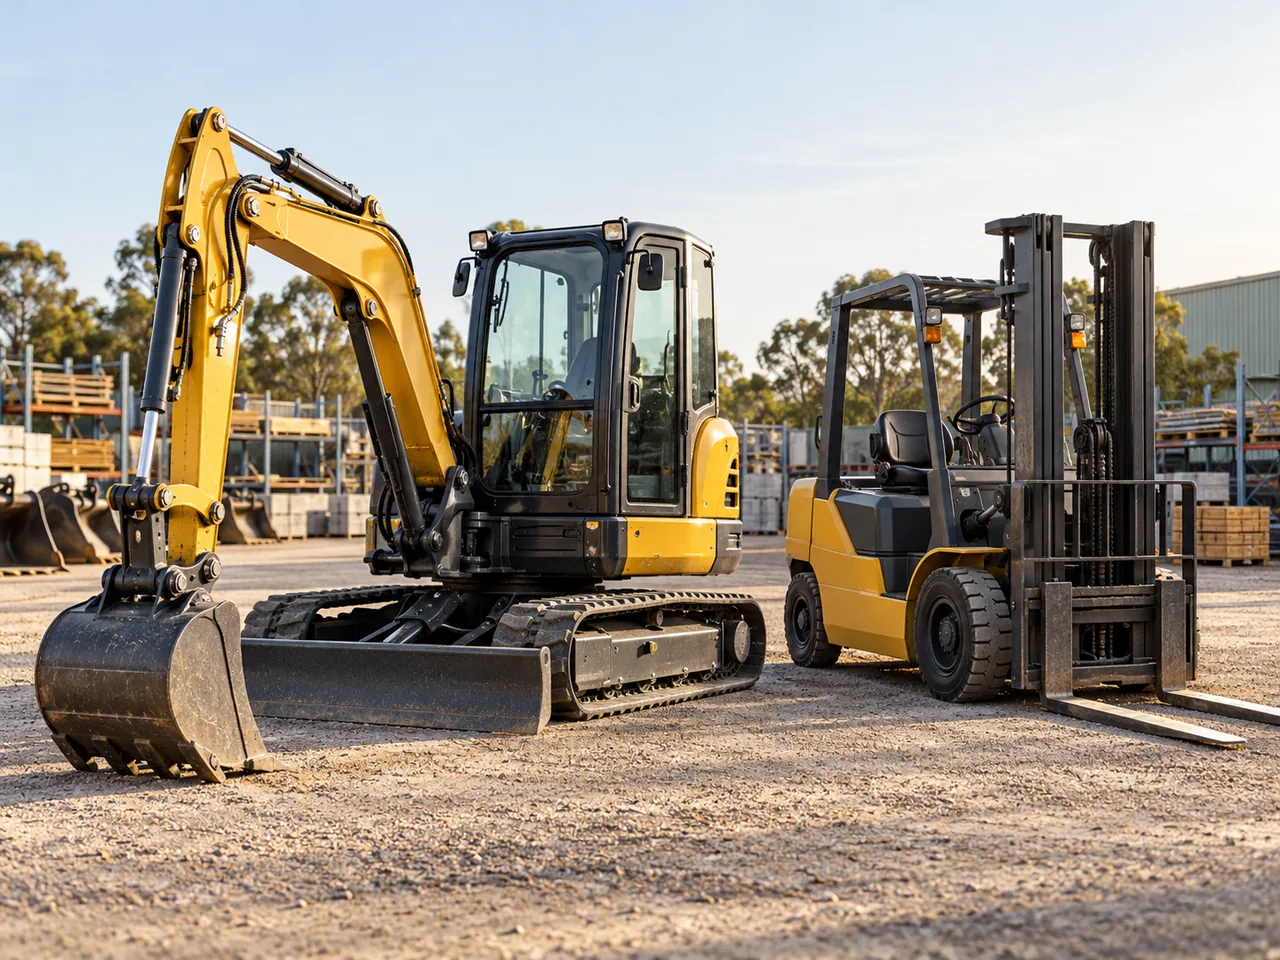
Start with the equipment and the work it will perform. Separate the asset price from installation, delivery, maintenance and other operating costs. Ownership, security, any deposit and a final balloon or residual depend on the proposed finance structure.
These explanations help you understand the differences. They do not select a product for you.
Borrow a set amount and repay under an agreed schedule.
Keep in mind: Match the repayment schedule to realistic business cash flow.
Explore this option →Draw funds up to an approved limit under the facility terms.
Keep in mind: Check drawdown rules, interest, fees and limit review conditions.
Explore this option →Access funding connected to eligible unpaid business invoices.
Keep in mind: Customer quality, invoice disputes, fees and collections arrangements matter.
Explore this option →Fund supplies or orders within a business trading cycle.
Keep in mind: Check supplier payment dates, delivery risks and how the facility is repaid.
Explore this option →A business needs equipment to deliver work and wants to spread the purchase cost while budgeting for running costs.
The team would discuss the purpose, information available, costs and repayment obligations before any next step. This illustration is not a client story, offer or approval.
Check ownership, security, maintenance and insurance costs, and any final balloon.
business.gov.au: choosing funding ↗You don’t need to have every answer before contacting us. Start with your goal and our team will explain what information is needed.
These are conversation checklists, not the final application requirements. Our team will confirm the relevant records and periods.
Your goal, preferred timing, and any circumstances you would like us to understand. Share sensitive documents only through a verified, approved process.
No. A purchase funds an identified acquisition. Equity release or a sale-and-leaseback arrangement involves an asset already owned and requires separate checks of value, ownership, existing finance and the proposed contract. Availability needs assessment.
No. Tax treatment depends on the structure, business use and your circumstances. Ask your accountant about GST, deductions and ownership before choosing a facility; any tax outcome should be checked separately from the finance quote.
Yes. Describe the equipment, expected cost and how it will be used. A supplier quote helps once you have selected an asset.
Tell us its age, condition, seller and price. Acceptance and terms depend on the equipment and assessment.
Tell us about existing balances, repayments and security arrangements. These are relevant to understanding the new request and your commitments.
These depend on the product and your individual assessment. Ask for the rate, fees, repayment schedule and total cost in the proposed terms before deciding.
Yes. Choose the short enquiry to share your goal and contact details, or take the full application path if you have more time. The team can clarify what is needed next.
Share a little about your plans, or complete the full application if you’re ready.
Choose how to get started →