Unsecured personal loan
Borrow without using an asset as security.
Keep in mind: Repayment obligations remain. Compare fees, interest and the full cost.
Explore this option →Explore a portable home purchase with the asset, installation and site arrangements considered together.
Explore the information first. Our team can help you understand the next step.
The initial review does not involve a hard credit enquiry. If you choose to proceed, a formal credit application may involve a hard enquiry, which can affect your credit score.
Tell us about the asset and the budget you have in mind. Our team can explain what information is needed and discuss possible next steps after review.
These explanations help you understand the differences. They do not select a product for you.
Borrow without using an asset as security.
Keep in mind: Repayment obligations remain. Compare fees, interest and the full cost.
Explore this option →An accepted asset supports the loan.
Keep in mind: The asset may be sold if repayments are not met. A lower total cost is not guaranteed.
Explore this option →Prepare the asset details, seller information and an itemised budget.
Keep in mind: Finance does not replace condition, compatibility or ownership checks.
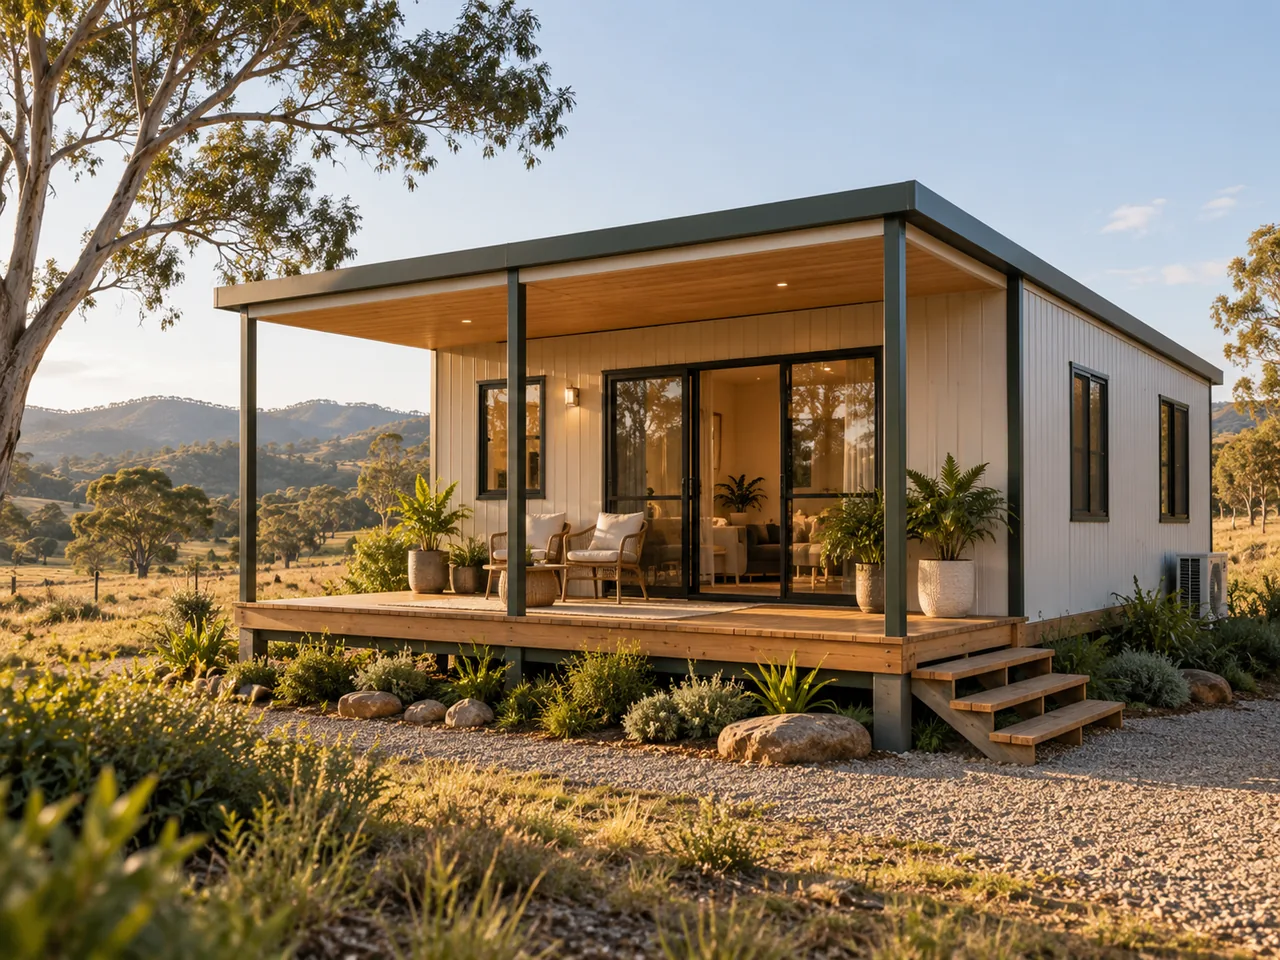
Explore this option →You are exploring a portable home on a leased site and need to understand the asset, land rights and possible funding pathway.
The team would discuss the purpose, information available, costs and repayment obligations before any next step. This illustration is not a client story, offer or approval.
A portable home is not automatically treated like a caravan or a standard home loan. Site rights, approvals and finance need separate review.
ASIC Moneysmart: personal loans ↗You don’t need to have every answer before contacting us. Start with your goal and our team will explain what information is needed.
Purchase and installation costs, specifications, site ownership or lease details, approvals and intended use.
Self-employed and applying for a car for personal use, a personal loan or another eligible consumer purpose? If your last two years of tax returns are not yet complete, an accountant’s letter may be accepted as the income document for eligible finance options.
Ask our team about an accountant-letter-only income verification option. Identification and other standard application information may still be required. Availability is subject to product criteria, assessment and approval.
These are conversation checklists, not the final application requirements. Our team will confirm the relevant records and periods.
Your goal, preferred timing, and any circumstances you would like us to understand. Share sensitive documents only through a verified, approved process.
No. Asset finance, land ownership or lease rights, installation and planning or occupancy permissions are separate matters. Check site agreements and approvals with the relevant parties before paying a deposit or relying on a funding outcome.
Yes. Tell us your approximate budget and preferred timing. A quote and asset details will help once you have chosen one.
Explain the site arrangement, ownership, installation and whether the home can be moved. These details need individual finance and legal review.
Tell us who is selling and provide the asset details. Seller and asset requirements need to be confirmed before you commit.
These depend on the product and your individual assessment. Ask for the rate, fees, repayment schedule and total cost in the proposed terms before deciding.
Yes. Choose the short enquiry to share your goal and contact details, or take the full application path if you have more time. The team can clarify what is needed next.
Share a little about your plans, or complete the full application if you’re ready.
Choose how to get started →